
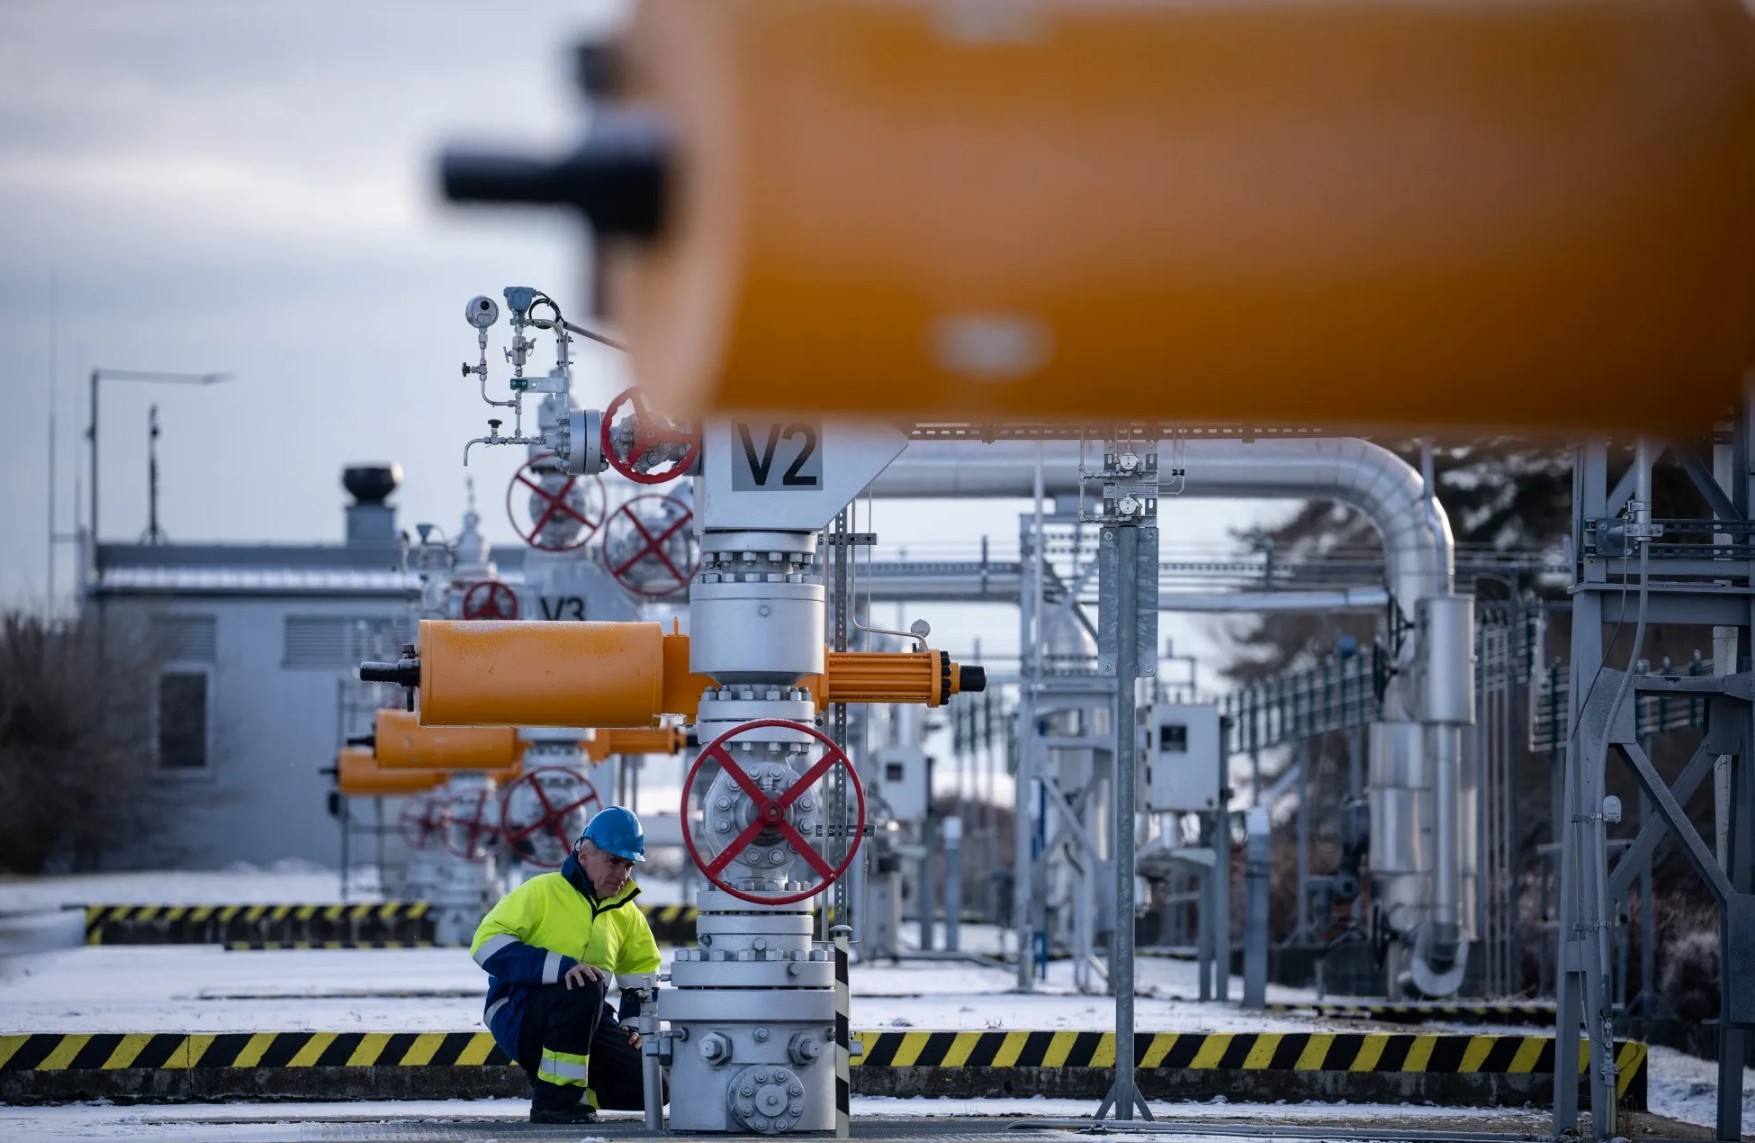
LONDON (Realist English). European natural gas prices on October 20 exceeded €90 per megawatt-hour for the first time in almost four years. November futures on the Dutch TTF hub rose as much as 2.5% to €90.24 per MWh, equivalent to about $1,063 per thousand cubic meters. This is the highest level since December 2022 and roughly three times higher than prices before the US-Israeli war with Iran began.
Reasons for the rise
Three factors determine the current dynamics. The first is disruptions to LNG supplies from the Persian Gulf. In 2025, the region accounted for about one-fifth of global liquefied gas exports, and maritime shipping through the Strait of Hormuz remains disrupted due to the conflict.
On October 20, Iran’s Islamic Revolutionary Guard Corps reported that two tankers caught fire and were immobilized after hitting mines south of Hormuz, heightening concerns about the timeline for restoring normal supplies.
The second factor is low storage levels. According to Gas Infrastructure Europe, as of October 19, EU storage facilities were 74.6% full — significantly below the usual 90% for this time of year and the lowest since 2011. In Germany, the continent’s largest economy, the fill level is just over 61%. Europe is entering the heating season already consuming gas but unable to replenish reserves to target levels.
The third factor is competition with Asia. LNG prices in North Asia have also surged to their highest since 2022, and European buyers are forced to offer higher prices to redirect cargoes from the US and other regions.
Forecasts
Rabobank analysts note that the worsening geopolitical situation could lead to further price increases in the short term. Igor Yushkov, an expert at the Financial University, allows for a rise to $1,200–1,500 per thousand cubic meters in winter.
According to the Oxford Institute for Energy Studies, if there is no diplomatic progress and LNG supplies from the Middle East are not restored before winter, European futures could exceed $30 per million British thermal units by March 2027.
However, there is a mitigating factor: mild weather in October allowed European companies to replenish stocks faster than usual. If the winter turns out mild, prices could fall to €40 by the end of the heating season, but in cold weather they could rise above €70 again.
Significance and consequences
The current price rise is not a one-off spike but a reflection of structural deficit. Europe is entering winter with the lowest reserves in 15 years, amid disrupted supplies from the Persian Gulf and growing competition with Asia for the remaining LNG cargoes.
Unlike the 2022 crisis, caused by the rejection of Russian pipeline gas, the current shock has a different nature: the maritime corridor through which liquefied gas from Qatar and the UAE flows has been disrupted.
This means that even under favorable developments, Europe will emerge from winter with depleted storage, requiring large-scale gas purchases in the summer of 2027 — and likely keeping prices high next year as well. For consumers, this means higher bills: in Germany, tariffs for new customers have already risen 55% since the start of the year.