
LONDON (Realist English). As of the Asian trading session on September 29, Brent futures rose more than 2% to $107.44 per barrel, while WTI gained 0.8% to $93.32. The previous day, Brent closed at $105.28, adding 0.9% for the session.
Double Pressure on the Straits
The most immediate driver of the rise is the simultaneous restriction of supplies through the Strait of Hormuz and the Bab-el-Mandeb Strait.
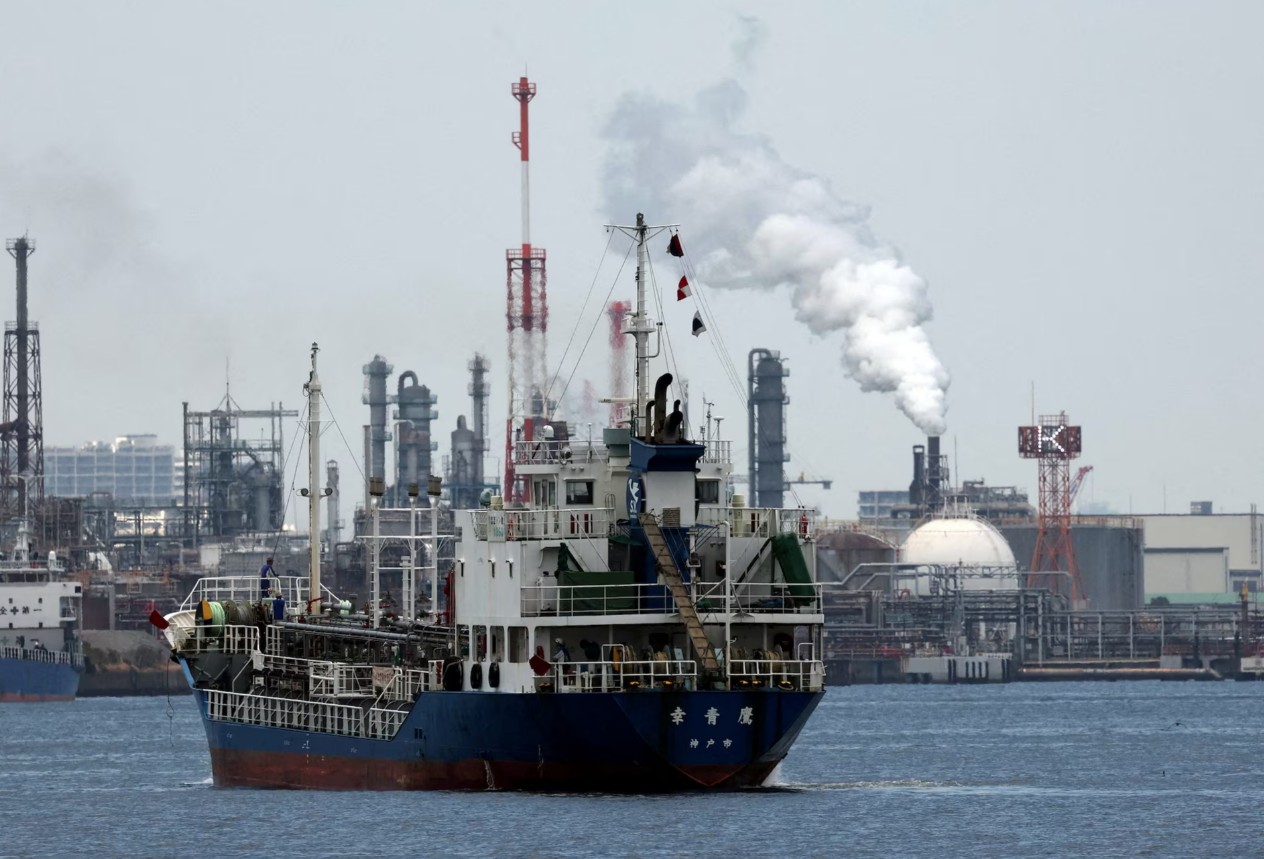
Transportation through the Strait of Hormuz has partially recovered — Middle Eastern oil exports have returned to roughly 80% of the pre-war level — but attacks on vessels continue, and transit risks have not been eliminated. The key problem is that Saudi Arabia’s main alternative route — the East-West Pipeline — was closed on September 10 after a drone attack.
This pipeline connects Saudi Arabia’s eastern oil fields with the port of Yanbu on the Red Sea. Its capacity is about 7 million barrels per day. It is a critical “safety valve” that allows Riyadh to maintain exports when Hormuz is blocked.
The pipeline’s shutdown means Yanbu can only ship from inventories sufficient for 5–7 days of exports. Saudi Aramco has canceled some orders from European refineries for late September and notified buyers of shipment delays.
Buffer Stocks Are Depleting
Unlike previous geopolitical spikes, the structural risk of the current rally is that available buffer stocks have noticeably shrunk.
Huatai Securities analysts note that commercial inventories before the current conflict were significantly lower than before the first round of the Hormuz strike. This means that with the same scale of disruption, the blow to the spot market could be stronger. A direct market signal: spot is rising faster than futures — traders are willing to pay a premium for “oil that can be obtained immediately.” This points to a real concern about a shortage of physically available oil, rather than distant risks.
IEA data confirm this picture: since February, total global oil inventories have fallen by 507 million barrels, including a 65 million decline in seaborne inventories in transit. The EIA forecasts that US distillate inventories will drop below 100 million barrels in October — the lowest since 2003.
Diesel Is the More Vulnerable Link
Tension in the diesel market is even higher than in the crude oil market. According to the IEA, in August diesel exports from Gulf countries fell to 390,000 barrels per day — a quarter of the pre-war level. US diesel futures exceeded $200 per barrel, rising 94% since the start of the conflict; the diesel crack spread surpassed $100 per barrel for the first time in history. The diesel shortage can transmit to the broader economy through transportation costs.
A Signal of Improvement: Partial Pipeline Restoration
On September 28, the Saudi East-West Pipeline resumed operation. The current flow is about 3.5 million barrels per day — roughly half of design capacity. This adds an important alternative supply channel to the global market and is a direct positive for European buyers. However, reaching full capacity will take time, and security risks in the Strait of Hormuz and the Red Sea have not disappeared.
Outlook
Huatai Securities raised its forecast for the average Brent price in 2026 from $86 to $90 per barrel, noting that even if geopolitical risks subside, the current shock could lift the central price trajectory for several quarters ahead. In the short term, under conditions of “double pressure on the straits” and “depleting buffer stocks,” oil is more likely to rise than fall: a price above $100 may become a new operating range rather than a short-term spike.