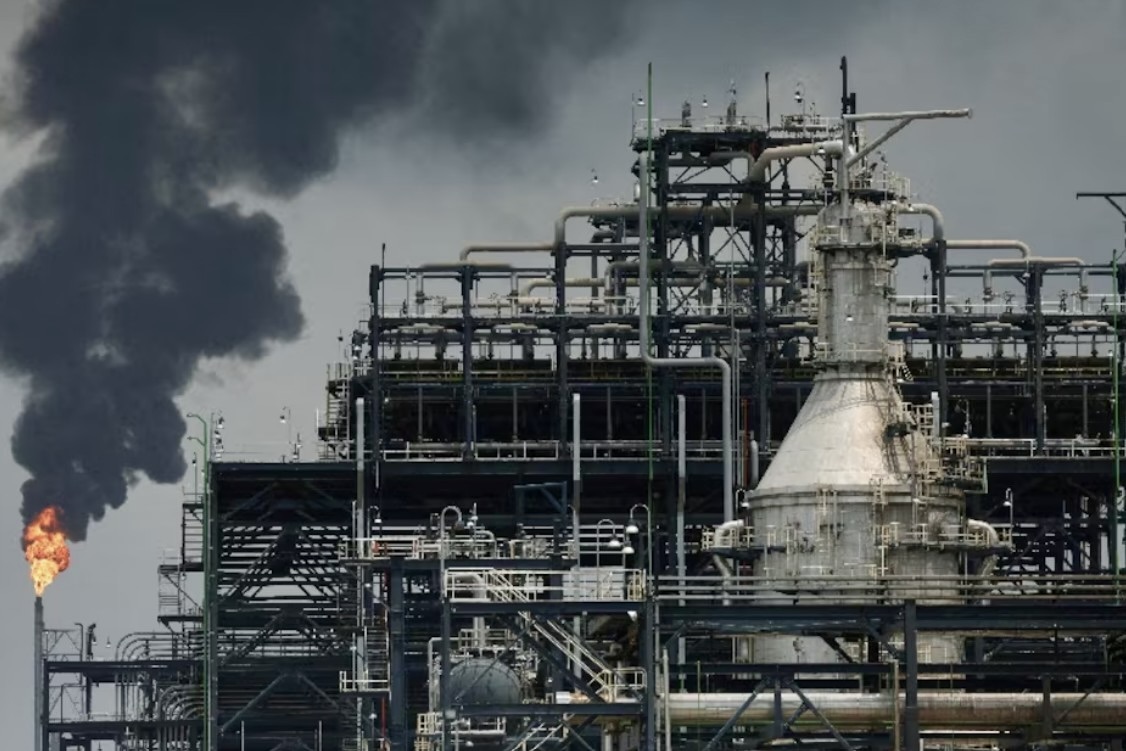

RIYADH (Realist English). Global oil prices continued to decline. The key theme of trading was the easing of concerns over the shutdown of the Saudi East–West pipeline (Petroline) following a drone attack on 10 September. The Saudi side has signalled a speedy restoration of export capacity, and this outweighed alarm over escalation of the Middle East conflict.
Scale of the Decline
The decline has a quantitative expression. As of the Asian trading session on 18 September, Brent fell by $2.14, or about 2%, to $102.68 per barrel.
According to some sources, during trading the price dropped to $102.53. WTI lost $1.83, or about 1.8%, and traded at $100.08 per barrel. Intraday, the price briefly dropped below the $100 mark, reaching a low of $96.2.
Both benchmark grades closed lower for the third day in a row. Over the week, Brent lost about 2% and risks ending the week with its first weekly decline in three weeks. At the same time, prices still remain above $100 per barrel — the geopolitical risk premium has not fully disappeared.
Three Signals of Easing Concerns
The first is progress in restoring the pipeline. The East–West pipeline was closed after a drone attack on 10 September. This route allows Saudi Arabia to bypass the Strait of Hormuz and supply oil to the port of Yanbu on the Red Sea.
Its length is about 1,200 km, and peak capacity reaches 7 million barrels per day. Earlier, the market feared that restoration would take up to 6 weeks, and that stocks in Yanbu would suffice for only 5–7 days of exports. The latest reports indicate that Saudi Arabia expects to restore about half of the pipeline’s capacity within a few days.
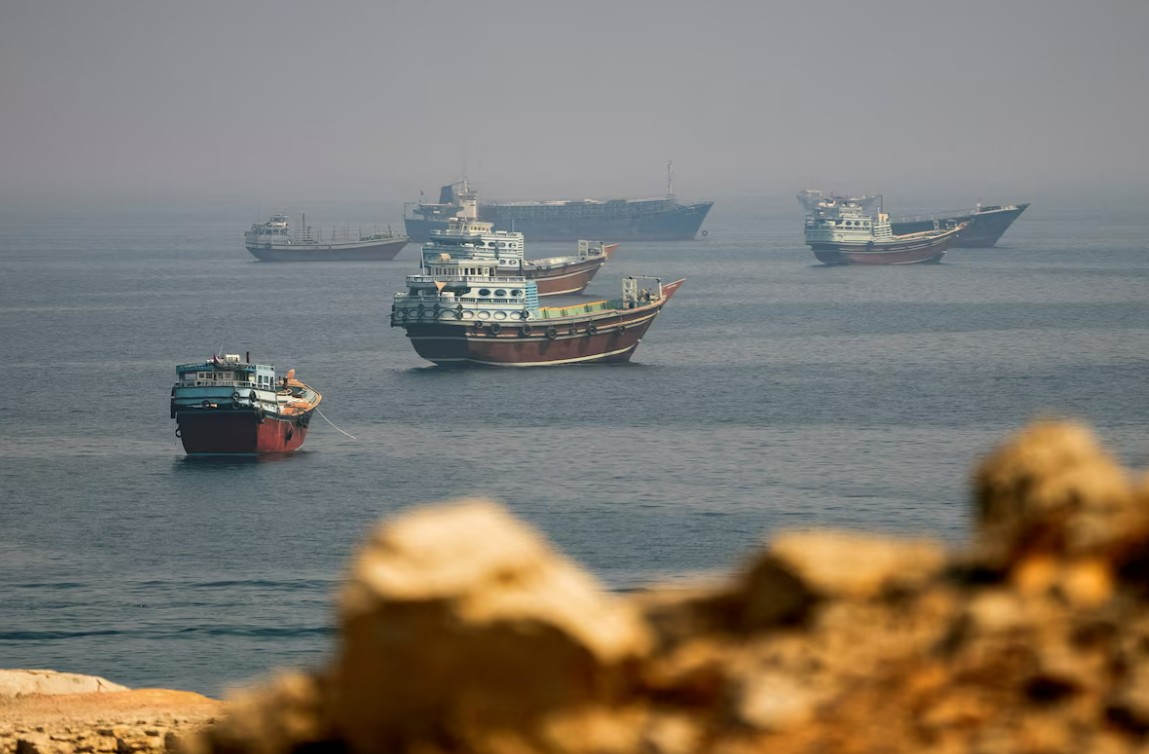
The second is alternative export routes. Saudi Aramco has already begun supplying oil to Asian refineries via ship-to-ship transfer near the Omani port of Sohar. This bypass route cannot fully replace the pipeline’s capacity, but it proves that Saudi Arabia is able to diversify export risks and prevent a complete halt in supplies.
The third is inventory data. According to the US Energy Information Administration (EIA), last week US crude oil inventories declined less than expected, while gasoline and distillate inventories rose. Again Capital partner John Kilduff noted that these data indicate that petroleum product supplies are not as tight as the market had feared. This created additional downward pressure on prices.
How the Crisis Developed
The current volatility is the result of a chain of events a week earlier. On 10 September, sections of the East–West pipeline near Riyadh and Medina were attacked by drones from Iraq.
The Saudi Ministry of Energy immediately took preventive measures and halted pumping. On 11 September, the Saudi Foreign Ministry condemned the attack but decided not to respond with military force, giving the Iraqi government time to investigate and settle the matter.
Before the attack, due to the blockade of the Strait of Hormuz amid the US-Iran conflict, Saudi Arabia had used this pipeline as its main alternative export route, pumping about 4 million barrels per day. After the attack, loading operations at the port of Yanbu were suspended, and Saudi Aramco cancelled part of the orders from European refineries for oil supplies in the second half of September.
What Next
Despite the short-term easing of concerns, analysts generally remain cautious. Brent is still trading above $100, which suggests that the geopolitical risk premium has not disappeared. Citibank believes that Middle East tensions will continue to support oil prices in the short term — until the possible opening of the Strait of Hormuz in the fourth quarter.
The actual pace of pipeline restoration remains a key variable. If Saudi Arabia fails to fulfil its promise to restore half of its capacity within a few days, oil prices may again receive upward momentum.
The market is re-evaluating the balance between panic over supply disruptions and Saudi Arabia’s ability to respond. At present, the advantage lies with the second factor, but any delay in restoration could quickly reverse this trend.