
MOSCOW (Realist English). The European Union is entering the autumn-winter period with critically low gas reserves.
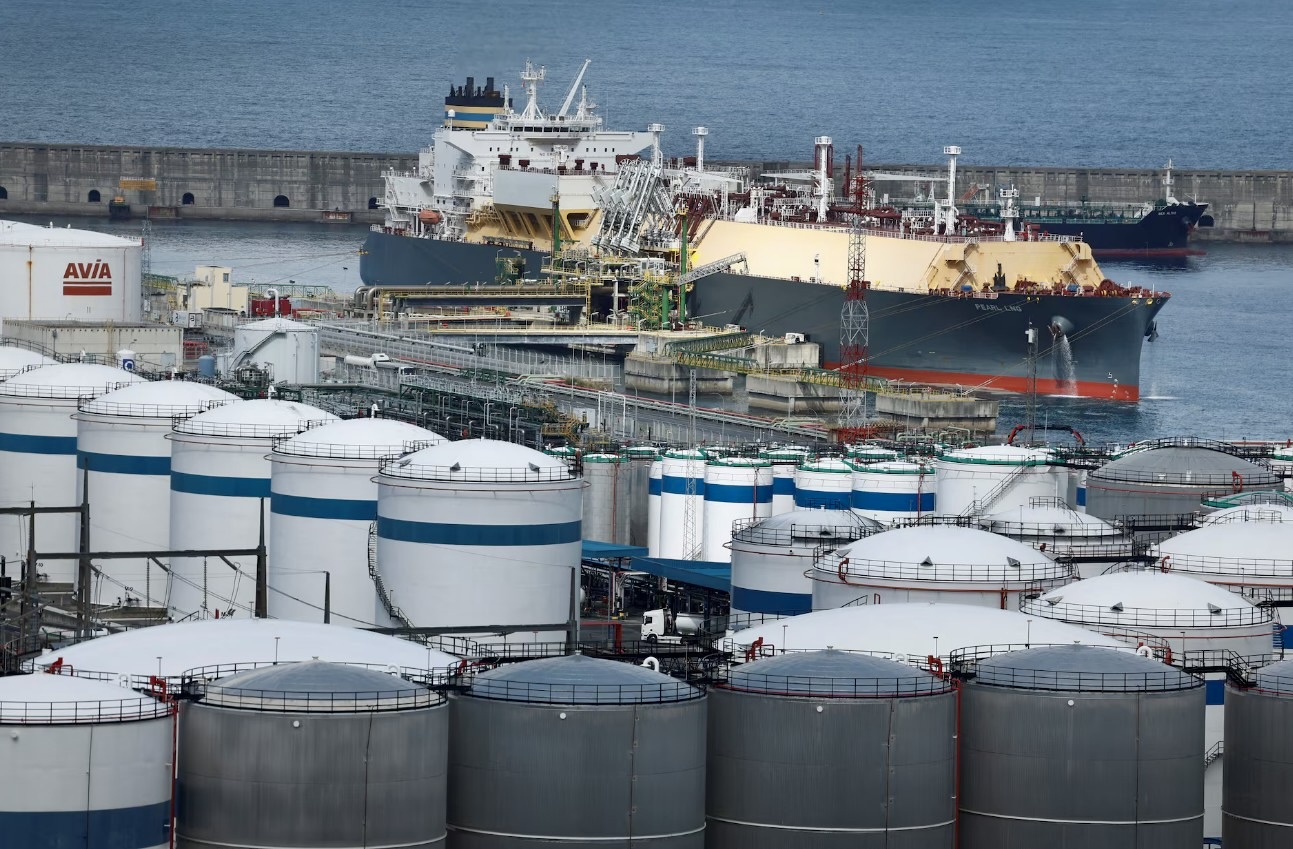
According to Gas Infrastructure Europe, as of September 7, EU underground storage facilities were 67% full — the lowest figure for this date since observations began in 2011.
In absolute terms, storage facilities held about 71.65 billion cubic meters of gas — 14 billion less than a year earlier.
Record Prices and Frantic Pumping
Amid the shortage of reserves, European companies are forced to inject gas into storage at record rates, which in itself drives up prices. In early September, average daily injection rates were among the highest in recent years.
Gas prices at the TTF hub in the Netherlands exceeded $1,000 per thousand cubic meters for the first time since December 2022, reaching $1,004 during trading. In mid-September, quotes held near $982, opening trading at $972.
Expert at the Institute for Energy and Finance Aleksey Belogoryev explained the nature of this rise: “European companies are trying to accelerate the process as much as possible in order to bring the average EU reserve level to at least 75%.
At the previous injection rates in July–August, reserves would have reached only 70% by November 1. This increases current demand from Europe and, amid an acute LNG shortage on the market, pushes prices up.”
Causes of the Crisis: Hormuz, Qatar and Asian Competition
The key factor that drove Europe into this position was the disruption of supplies from the Middle East. The blockade of the Strait of Hormuz led to a reduction in LNG exports from the region by 85%.
Qatar, the largest supplier of liquefied gas, in the first quarter of 2026 reduced supplies to the Mediterranean almost by half — to 630,000 tons versus 1.21 million tons a year earlier.
Additional pressure came from hot weather in Asia, which increased demand for gas for cooling and redirected part of flexible LNG cargoes to the east. European buyers had to compete for the remaining volumes in conditions where the global market lost 15% of expected LNG supplies between March and August.
Germany — The Most Vulnerable Point
The situation is distributed extremely unevenly across Europe. Germany, the continent’s largest gas market, as of September 8 had storage facilities only 54.75% full — almost 10 percentage points below the EU average. For comparison: Italy has already exceeded 84%, France — 74%, Austria — 67%.
The Association of German Underground Storage Operators INES warned that at current rates the country’s reserves could be completely exhausted by February.
Political Pressure: Calls to Return to Russian Gas
Against the backdrop of looming shortages, voices in Europe are growing louder about revising energy policy. Russian President Vladimir Putin, commenting on the price rise, said the cost of gas could rise to $1,500 per thousand cubic meters, and noted that Europeans would probably regret their choice.
The European Commission, for its part, has already lowered the mandatory storage filling target from 90% to 80% by November 1, acknowledging that achieving the previous level under current conditions is impossible. Brussels insists that there will be no physical gas shortage in winter, but acknowledges the risks of price volatility.
Analysts expect that with a cold winter and continued tensions around Iran, prices could rise to $1,200–1,300 per thousand cubic meters. Even if the Strait of Hormuz opens soon, full price normalization is not expected within a year — low reserves will support additional demand.