
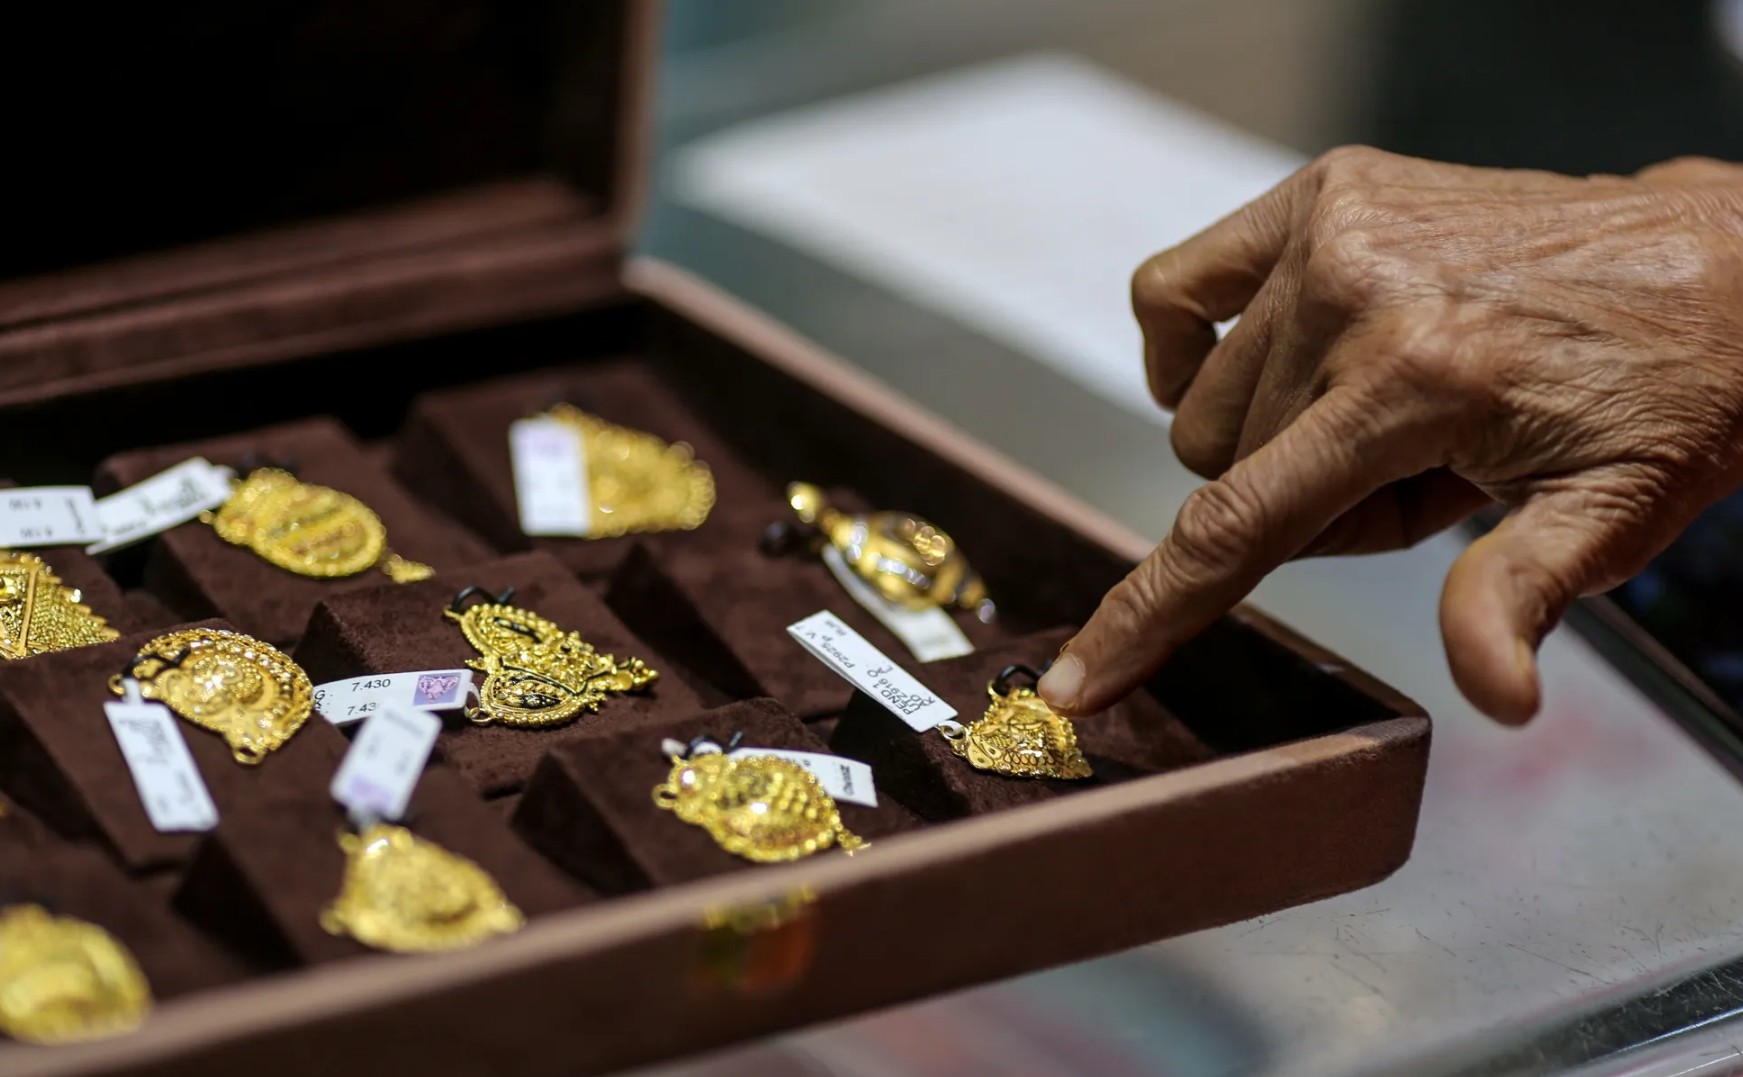
NEW DELHI (Realist English). The Indian gold market, which has endured a difficult year, is showing signs of recovery in the country’s key festive season. According to the All India Gem and Jewellery Domestic Council (AIGJDC), footfall and sales volumes have risen noticeably after gold prices corrected below the psychological mark of $4,000 per ounce. International gold quotes, which peaked at $5,600 per ounce in late January 2026, fell below $4,000 by late October — a decline of about 24% since the start of the US-Iran war in late February.
Festive optimism and price correction
Dhanteras, considered the most auspicious day for buying gold, fell in early November in 2026. Surendra Mehta, national secretary of the India Bullion and Jewellers Association (IBJA), expects demand this festive season to be 12% higher in volume terms than a year earlier and estimates gold sales at 51–52 tonnes versus about 46 tonnes last year. AIGJDC vice-chairman Avinash Gupta forecasts Dhanteras sales to rise 15–20% in value terms.
The revival comes after a sharp slump in previous months: according to Gupta, demand fell almost 40% over the past six months due to high prices. In May 2026, the Indian government more than doubled the import duty on gold — from 6% to 15% — further raising domestic prices. Nevertheless, the current correction in global quotes has created a sufficient price gap to bring buyers back.
WGC data: annual decline and quarterly recovery
According to the World Gold Council (WGC) report “Gold Demand Trends: India Focus, Q3 2026,” published on 3 November, total gold demand in India in July–September 2026 amounted to 162.5 tonnes, 29% below the same period in 2025 (229.8 tonnes). However, in quarterly terms, demand rose 24% compared to 130.9 tonnes in the second quarter.
The improvement was driven by the jewellery segment: jewellery demand in the third quarter was 99.9 tonnes, down 20% year-on-year but 33% above the previous quarter. The WGC directly links this to “the correction in gold prices at the end of the third quarter, which prompted some consumers to make deferred purchases,” as well as wedding and festive buying, especially in South India, where key festivals fell in August.
Investment demand remains weak: bar and coin demand fell 40% year-on-year to 55 tonnes, and gold ETF demand fell 50% to 5.3 tonnes. In the first nine months of 2026, jewellery demand declined 18% to 241.1 tonnes, while its value rose 29% to ₹3.61 trillion — Indian consumers are paying more but buying less gold in volume terms.
Imports and supply
Official gold imports in the third quarter slumped 70% to 64 tonnes, including doré. Net bullion imports totalled 114 tonnes, down 46% year-on-year. The WGC attributes this to weaker physical demand, inventory adjustments, higher duties and possible postponement of imports in anticipation of the festive season.
Of particular note is the rise in unofficial channels: according to WGC estimates, illegal gold inflows in the third quarter amounted to about 50 tonnes, compared with just 3 tonnes a year earlier.
This means official import statistics may understate the real volume of gold entering the country. Citi Research forecasts that gold imports into India in October–December will be about 106 tonnes — roughly half the historical average for the fourth quarter of 212 tonnes.
Structural shifts in consumer behaviour
High prices have changed not only the volume but also the nature of purchases. According to industry representatives, buyers are increasingly choosing lightweight jewellery, especially 18-carat gold, which reduces the effective purchase cost.
Gold exchange has become an important tool: consumers trade in heavier 22-carat items and buy modern lightweight 18- and 14-carat jewellery. Jewellers, in turn, are offering discounts on making charges and studded items to convert interest into sales.
Forecasts: six-year low and festive test
Despite the revival, the WGC forecasts that total gold demand in India for 2026 will be 625–675 tonnes — the lowest level since 2020, when pandemic lockdowns closed jewellery shops. Pressures include record-high prices, a weak monsoon (the driest in over a decade), which has hit rural incomes that account for more than half of demand, and the rising cost of living after the war with Iran.
The Diwali and wedding season will be the nearest test: according to Sachin Jain, head of WGC India, demand should recover in December, but high prices and a weak rural economy are likely to limit the scale of the rebound.
The festive spike in Indian gold demand is not a return to pre-crisis levels but rather deferred demand realised amid a price correction. The annual demand trajectory remains at a six-year low, and structural factors — the 15% import duty, the weak monsoon and rising living costs — continue to constrain recovery.
The key indicator will be not only sales volumes during Dhanteras and Diwali but also the sustainability of this momentum in December, when the wedding season ends. If high prices prevail again, the Indian market may return to stagnation, and the rise in unofficial imports will further distort the picture of real demand.