
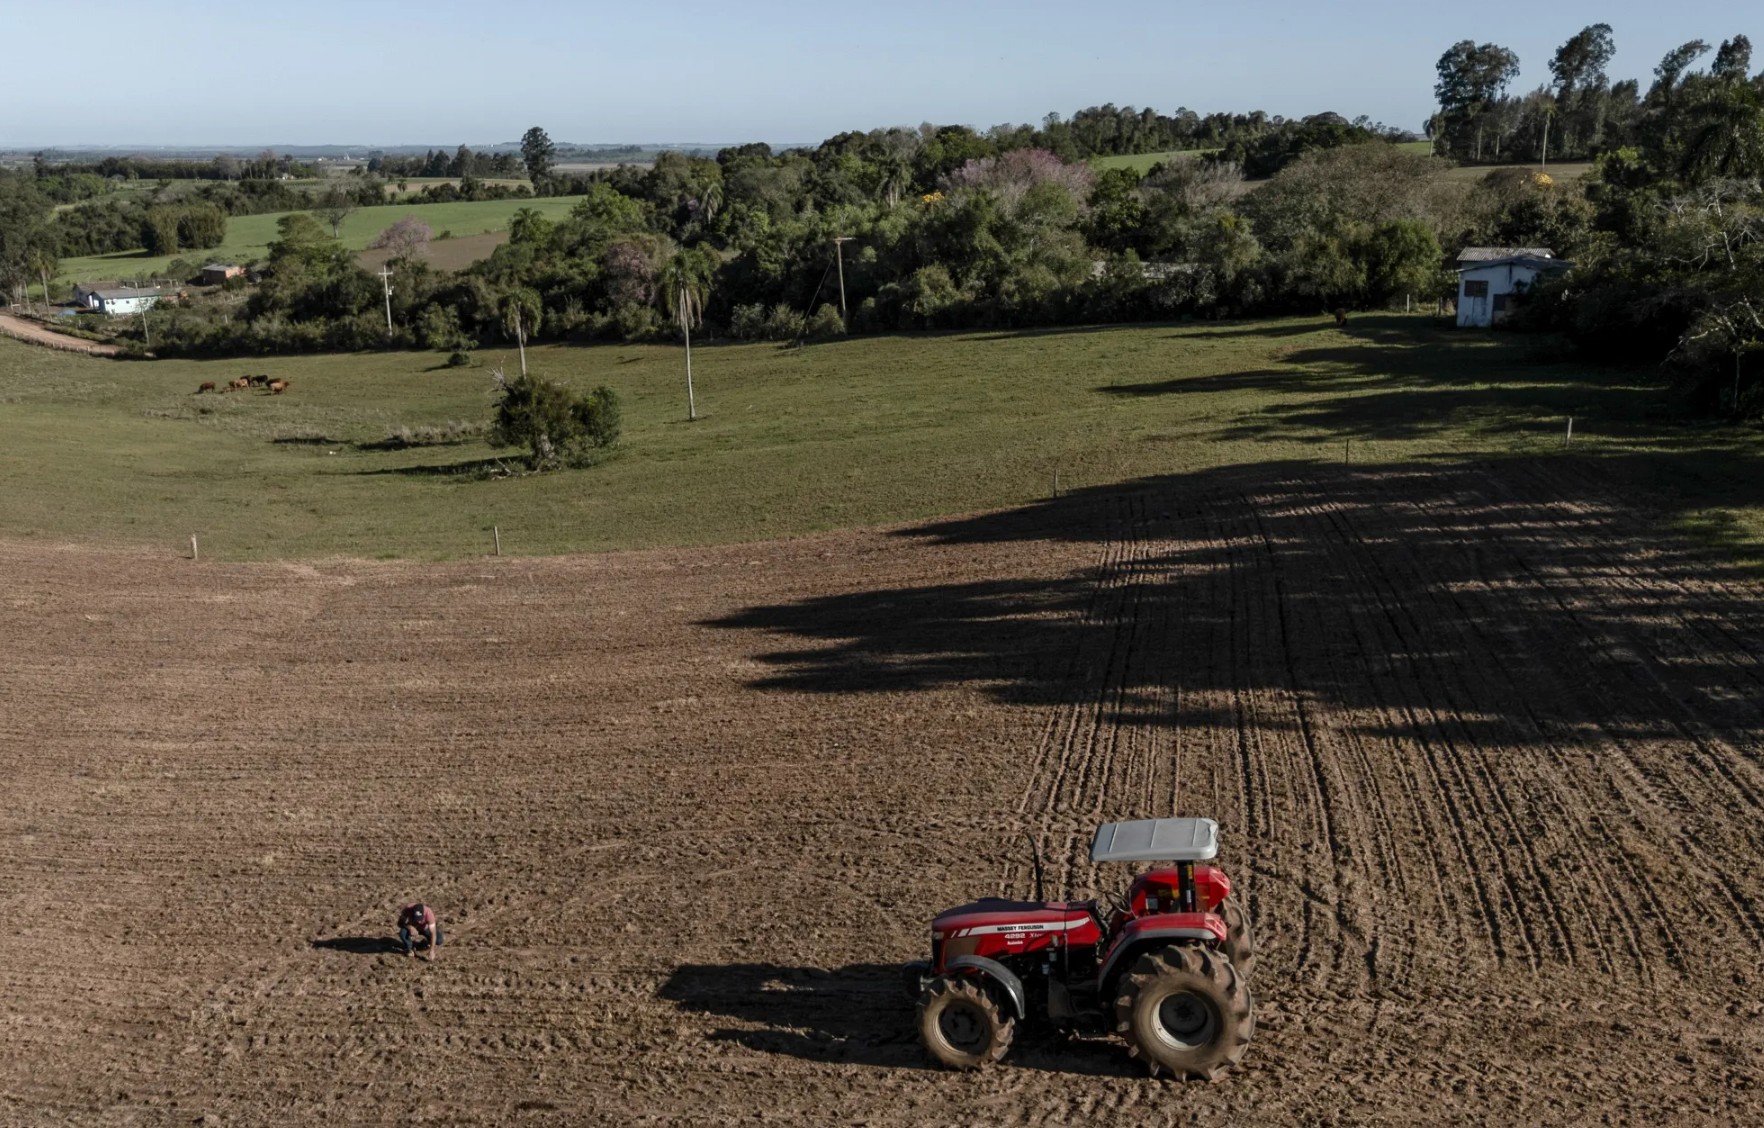
SÃO PAULO (Realist English). The victory of Luiz Inácio Lula da Silva in the presidential election on 25 October, where he won 51.79% of the vote against 48.21% for Flávio Bolsonaro, caused deep disappointment in Brazil’s agribusiness sector. Large producers and the agricultural lobby openly supported Bolsonaro, seeing him as a more natural ally of their interests. However, their concerns are linked not only to political preferences but also to a worsening debt crisis that had already become systemic before the elections.
Scale of the debt crisis
The financial position of Brazilian farmers is deteriorating rapidly. According to the Central Bank, as of July 2026, the total volume of agricultural loans issued was 885 billion reais, of which 208 billion reais were classified as “problematic.”
The amount of loans overdue by more than 90 days rose from 3.8 billion reais in July 2023 to 38.4 billion reais in April 2026 — almost a tenfold increase in three years. By June 2026, according to UOL, the volume of overdue debt reached 48 billion reais, which is 2,300% more than five years earlier.
A feature of the current crisis is that its centre has shifted toward large producers. Whereas previously the burden of overdue debt was distributed among all categories of farmers, now 29 billion reais of the total falls on high-income producers, whose debt has grown by more than 7,000% over five years. The share of overdue operations among individuals — who make up about 80% of the loan portfolio — reached 9.7% in August 2026, a historic high since 2011.
Market reaction and weakening of the real
Lula’s victory caused an immediate reaction in financial and commodity markets. The Brazilian real weakened by about 11% against the US dollar, which on the one hand increased the competitiveness of Brazilian exports, but on the other increased the domestic cost of imported resources, including fertilisers.
Prices for some of the world’s largest agricultural commodities fell sharply after Lula’s unexpected victory, increasing pressure on farmers’ incomes.
Traders, expecting continued active government spending under the new administration, reduced bets on an early rate cut and are now pricing in a resumption of monetary tightening. This creates additional pressure on producers already facing record overdue debt.
Causes of the crisis: rates, costs and weather
The debt crisis has several interrelated causes. The key Selic rate rose from 2% to 15% over five years, and the average annual rate on agricultural loans for individuals rose from 6.3% in 2021 to 12.2% in 2025. At the same time, farmers faced squeezed grain margins and repeated weather shocks, especially in the southern state of Rio Grande do Sul, where a catastrophic flood occurred in 2024.
The situation is aggravated by rising fertiliser costs, including due to the war with Iran. As a result, the number of applications for judicial protection from creditors (recuperação judicial) in agriculture rose by 66% in the first half of 2026 compared to the same period in 2025 — to 1,263 producers. According to Serasa Experian, bankruptcies in the agricultural sector jumped by 56% in 2025 after more than doubling in 2024. Auctions for the sale of seized farms rose by 30% in 2025, with the number of properties sold out of court almost doubling.
What is expected from Lula’s government
The agricultural lobby had pinned its hopes for debt relief on a Bolsonaro victory, which was expected to offer large-scale debt restructuring measures.
Now, according to Valor International, Lula’s re-election plan does not mention new measures to restructure rural debt, whereas for other sectors of the economy his administration has already announced a number of initiatives to ease the debt burden.
Nevertheless, the government has taken some steps. In July 2026, it announced plans to restructure more than 100 billion reais of rural debt, including a 30-day payment suspension for eligible producers. However, the temporary measure signed by Lula allocates only 26 billion reais (about $4.8 billion) to support subsidised loans and, according to critics, does not cover large creditors.
President of Aprosoja Mato Grosso Lucas Beber, commenting on the election results, called for a “structural solution” to the rural debt problem that would go beyond simply extending payment deadlines. He also pointed to a “worrying paradox”: record production and exports coexist with a financial crisis among farmers.
Lula’s victory did not create the debt crisis in Brazilian agriculture — it had been brewing for years due to high rates, rising costs and weather shocks. However, it deprived large producers of a political ally in the government and increased uncertainty about what support measures would be offered.
The market has already reacted with a weakening real and falling commodity prices, which gives exporters a temporary price advantage but at the same time makes imported resources more expensive. The key question is whether the Lula administration can offer a structural solution to the debt problem, rather than limiting itself to cosmetic measures, or whether the crisis will continue to deepen, creating risks for one of the pillars of the Brazilian economy. The upcoming harvest season and interest rate decisions will be an indicator of whether the situation can be stabilised.