
LONDON (Realist English). The global coffee market is shifting from deficit to surplus for the first time in four years, but this does not bring stability. Record harvest forecasts are colliding with depleted exchange stocks and climate risks that could negate the effect of new supply.
Record harvest versus empty warehouses
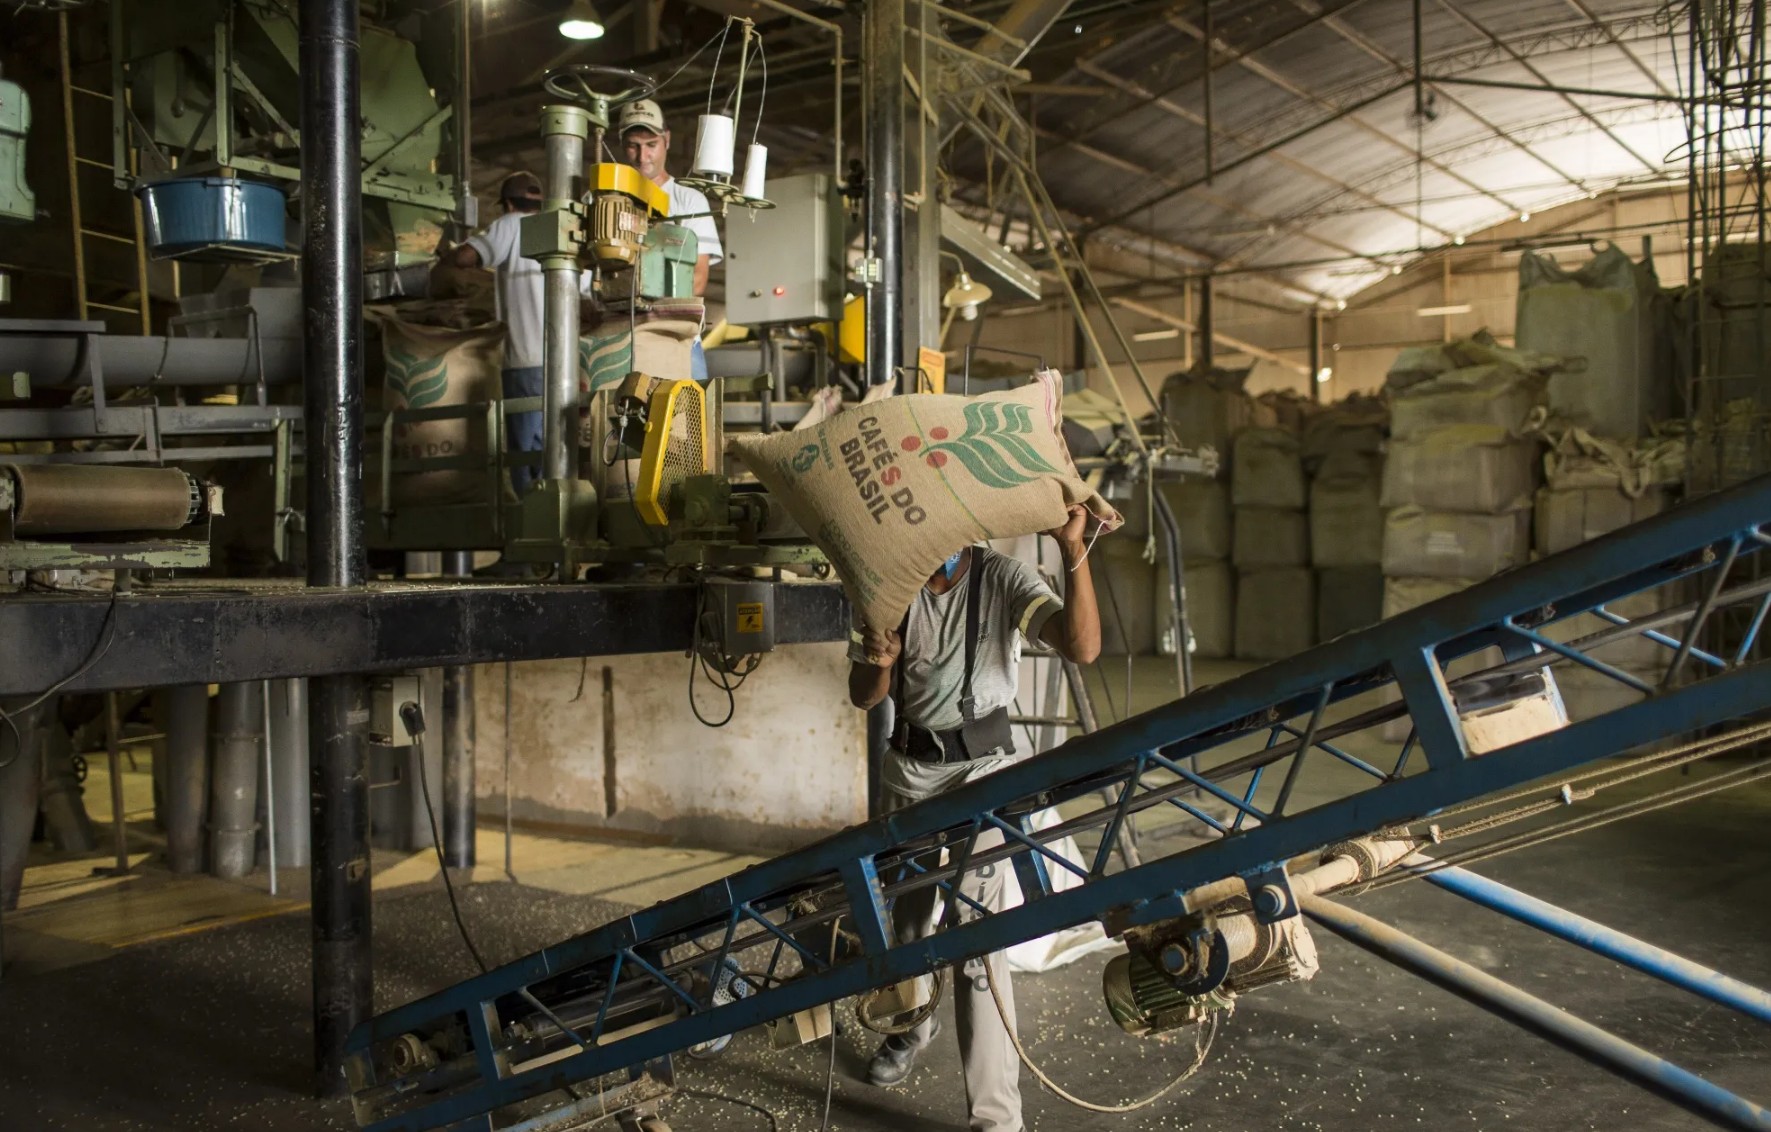
According to the July report from the US Department of Agriculture (USDA), global coffee production in the 2026/27 season will reach a record 189.7 million bags (60 kg each), 6% higher than the previous season. The main driver is Brazil with a forecast of 71.9 million bags, 14% more than a year earlier. Vietnam also expects a record 32.5 million bags, Ethiopia — 12.1 million, Uganda — 7.1 million.
However, record production does not mean abundance in the market. Certified arabica stocks on ICE have fallen to their lowest since 1999, making the market extremely sensitive to any supply disruptions. Global ending stocks, according to USDA forecasts, will rise only to 26.3 million bags — still below the historical norm.
Structural paradox
The key problem lies in the structure of supply. Production growth is driven mainly by robusta and Brazilian arabica, but does not solve the problem of depleted stocks of exactly the coffee that trades on the exchange. Brazilian arabica exports for the first nine months of 2026 fell 10.7%, while robusta shipments rose 68.3%. For the exchange arabica contract, this means that physical coffee of the right quality and in the right place remains scarce.
Climate factor: El Niño
Additional pressure comes from the threat of El Niño. According to the US Climate Prediction Center, the current phenomenon could become one of the strongest in 75 years. The concern is that delayed rains in Brazil in September–October — a critical flowering period — could hit the 2026/27 harvest. Rabobank analysts expect arabica prices to remain in the $2.5–3.0 per pound range by the end of 2026.
Farmers are holding back grain
Another factor distorting the market is the behavior of producers. After two years of climate shocks and record prices, farmers are in no hurry to sell their harvest, preferring to store grain in anticipation of better conditions. This creates an artificial deficit in the physical market even with formally sufficient production.
What this means
The global coffee market has moved from absolute deficit to fragile volume stabilization, but this does not mean a return to low prices. Exchange stocks are at a minimum, El Niño threatens the next harvest, and producers are holding back grain.
The record 2026/27 harvest may only slow price growth but not reverse the trend. For consumers, this means that retail coffee is likely to remain expensive — at least until global stocks recover to normal levels, which will take more than one season.